BaaS platform for regulated businesses: dedicated IBANs, a dashboard and an API
By Artem Balduk, Account Executive at PaySaxas
Your clients want euro accounts in their own names, not a reference on someone else's account. A BaaS platform lets you give them that without building the banking side yourself: the IBANs, the access to SEPA, the KYC and KYB checks and the safeguarding of client funds.
This guide explains the three ways to use the PaySaxas BaaS platform and how accounts in your clients' names will work. It also covers the dashboard, the API and what makes the platform different. It is written mainly for regulated businesses, such as EMIs, payment institutions, PSPs and MSBs. PaySaxas BaaS is coming soon.
What a BaaS platform does
Banking as a Service (BaaS) splits the work between three parties:
- The provider, a licensed institution, holds the accounts, issues the IBANs, connects to the payment rails and runs the compliance checks.
- You, the partner, bring the clients and the relationship, and work with the accounts from your own operations or product.
- Your clients hold the accounts and use them every day.
The BaaS platform is what connects you to the provider: a dashboard for your team and an API for your product.
Most providers promise the same thing: accounts for your clients through an API. However, the details differ. Whose name is on the account? Where does the money sit? Who approves the payments? And how much of the work stays with you?
Three ways to use the PaySaxas BaaS platform
The PaySaxas BaaS platform serves three kinds of business through the same dashboard and API:
- Accounts in your clients' own names. This is for licensed firms. Each of your clients opens its own PaySaxas account with a dedicated IBAN and becomes a PaySaxas client too. You keep the relationship and manage the account under your client's mandate.
- Your clients' money in accounts in your name. This is for licensed firms that hold client money themselves. You keep that money in client-funds accounts, apart from your own, and run them from your own platform. Your clients stay your clients, so you check them and meet any safeguarding rules under your own licence. An EU or UK firm cannot count an account with us as its safeguarding account, because we are an EMI, not a bank.
- Your own accounts, automated. This is for any business client of PaySaxas. Your systems work with your own accounts: payouts from your ERP, incoming payments in your ledger and a notification when money arrives.
In all three cases, every account is a real account with a Finnish IBAN in the holder's own name. There are no virtual IBANs and no master account.
How the PaySaxas BaaS platform works
For accounts in your clients' own names, the PaySaxas BaaS platform works in four steps:
- You become a partner. Before your first client, we onboard your business: due diligence, a check of your licence or registration and a BaaS agreement. Your business also holds its own account with PaySaxas.
- Your client applies. You introduce your client from your dashboard, or from your product through the API. With your client's consent, you can share the checks you have already done, so your client does not start from zero. This works only with partners we can rely on: firms in the EEA, or in a country with equivalent rules, approved one by one. Other partners can introduce clients, and we do our own full checks on each one. In either case, your client confirms its details and accepts our terms itself.
- The account opens in your client's name. We run our own KYC or KYB checks and make the decision. Each approved client gets its own PaySaxas account with a dedicated Finnish IBAN. You see the status of the application where your client agrees to share it.
- You manage the account under your client's mandate. The mandate is your client's permission to work with its account, and your client can withdraw it at any time. Within it, you handle payments, statements and reports in the dashboard or through the API.
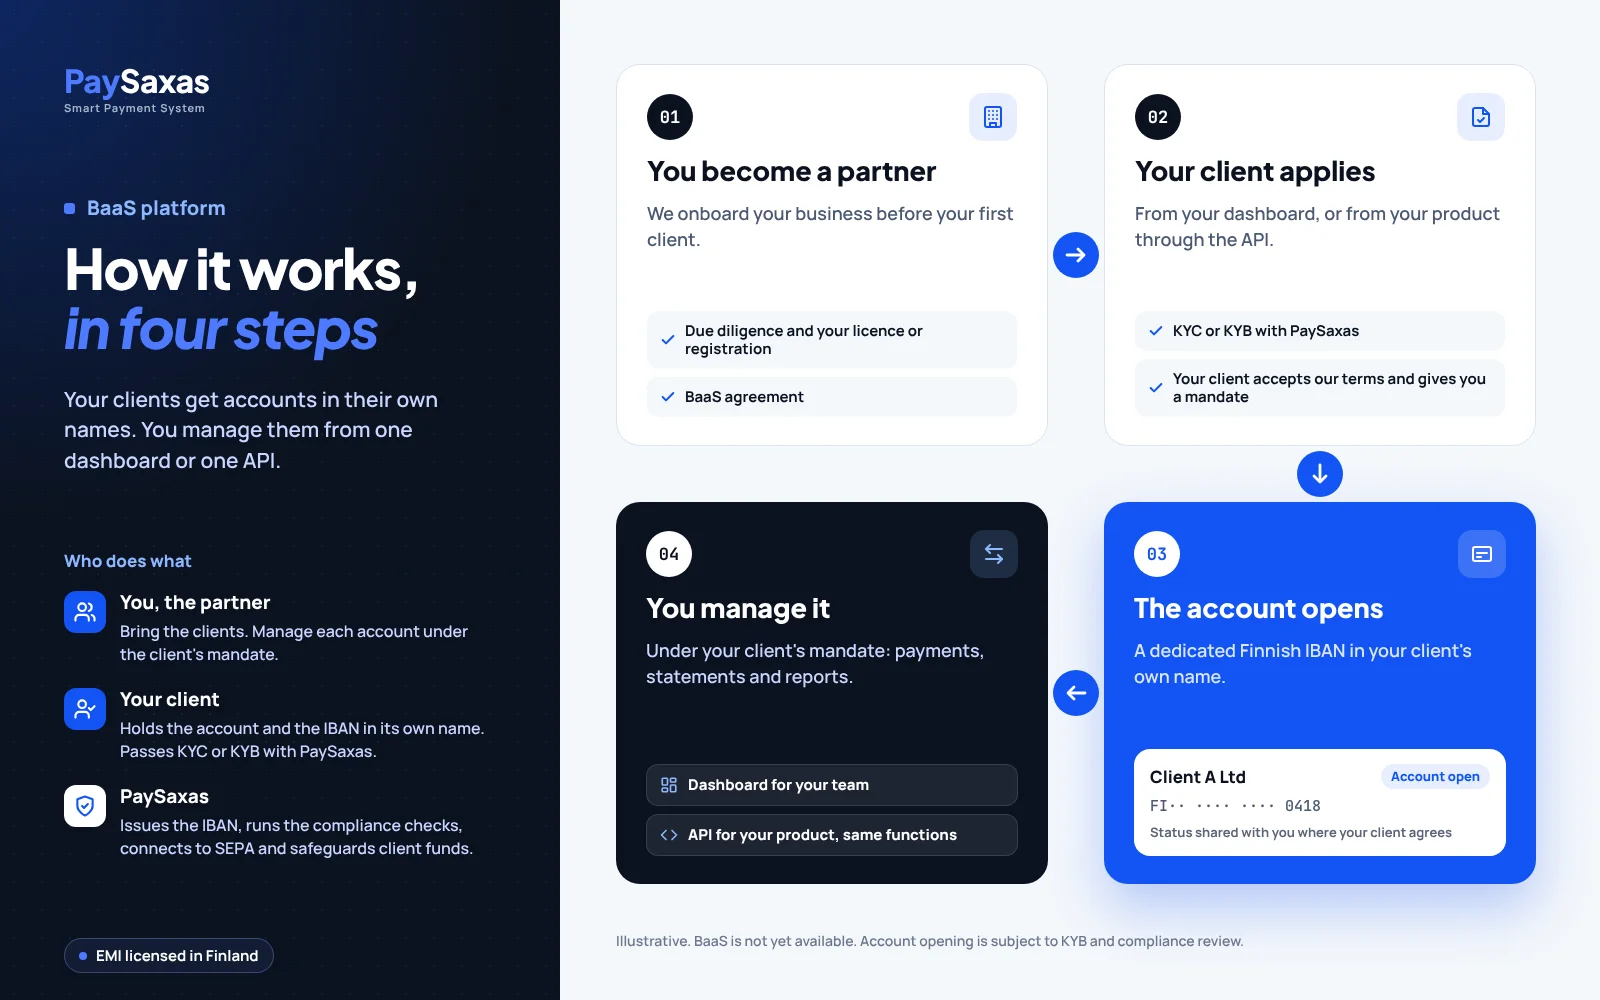
Your client holds the account and has its own contract with PaySaxas, while you keep your own relationship with the client. Its money stays in its own account and is safeguarded, apart from your own accounts.
One dashboard and one API
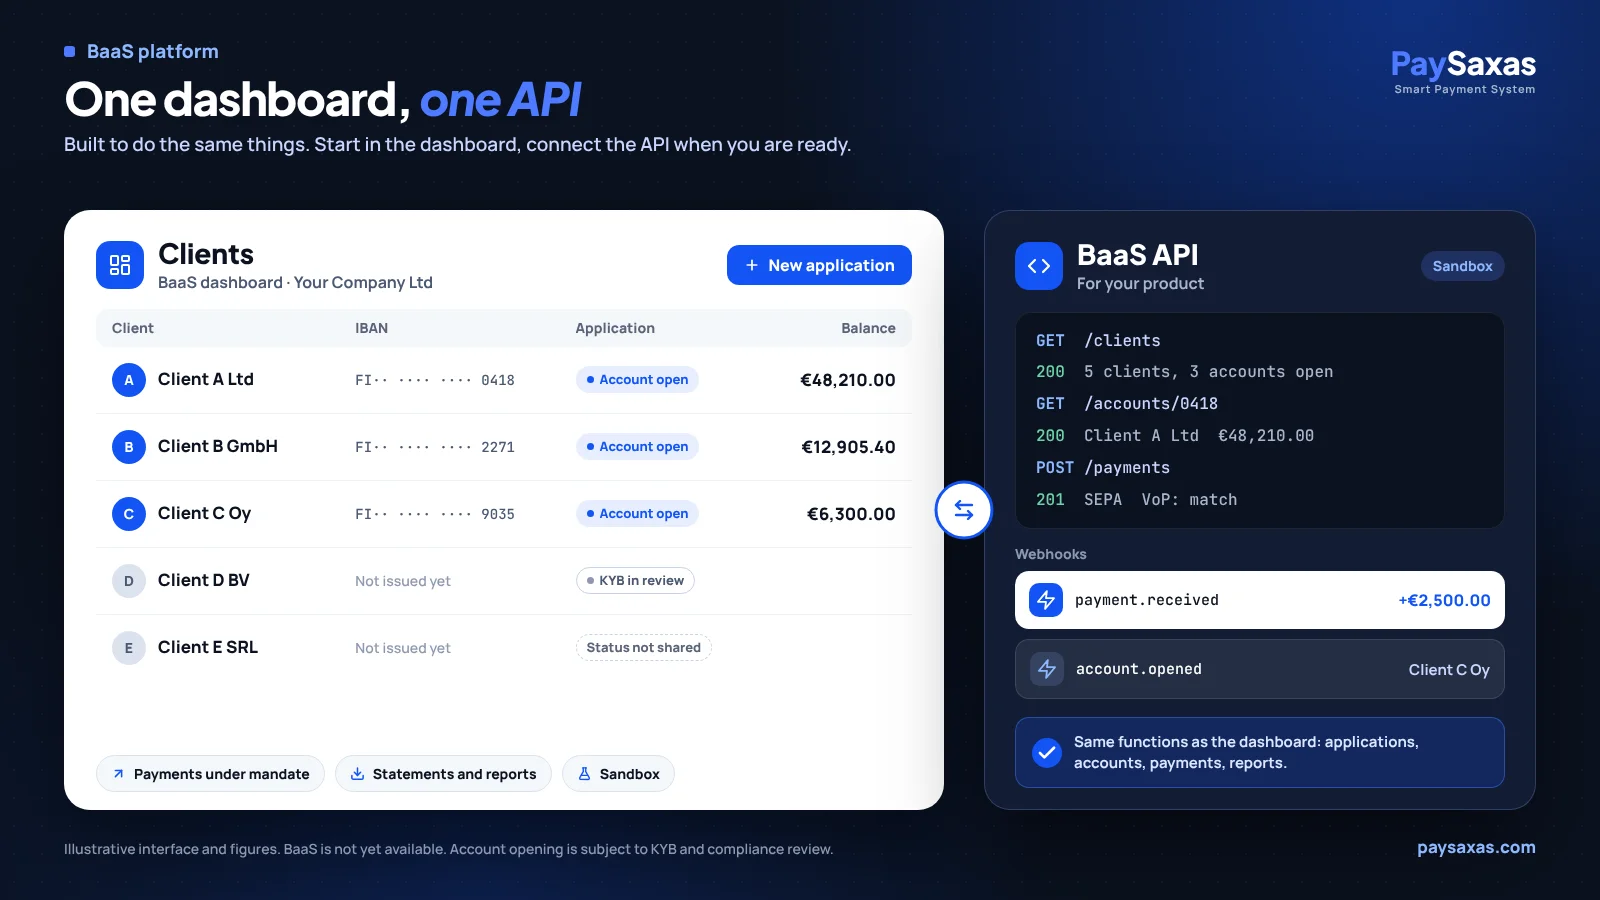
The PaySaxas BaaS platform gives you two ways to work: a dashboard for your team and an API for your product. Both are built to do the same things, so you can start in the dashboard and move to the API when you are ready, or use both.
The BaaS dashboard
For your operations, finance and compliance teams:
- All your clients in one list, with the status of each application where the client agrees to share it.
- Each client's account and IBAN, with balances and payment history.
- Payments prepared under your client's mandate, with Verification of Payee before each payment leaves.
- Statements and reports to download for your reconciliation.
- Team access by role, so each person sees and does only what their work needs.
- A sandbox to try the flows before you work with real accounts.
The BaaS API
For your developers and your product:
- The same functions as the dashboard, such as applications, accounts, payments and reports.
- Batch payouts, to pay many recipients in one go.
- Webhooks, so your system learns about events, such as an incoming payment, without asking.
- A sandbox to build and test your integration before you connect real accounts.
- Reporting and reconciliation data for your back office.
Want to see how this would work for your clients? Talk to us.
Virtual IBAN vs dedicated IBAN
Many BaaS providers give clients virtual IBANs. A virtual IBAN is a reference that routes payments into a master account. As a result, the money sits in that master account, and the provider's records show which payment belongs to which client.
PaySaxas does not use virtual IBANs. Instead, each client gets its own account with its own Finnish IBAN and its own balance.
| Virtual IBAN | Dedicated IBAN at PaySaxas | |
|---|---|---|
| What it is | A reference that routes payments into a master account | An account of its own, with its own IBAN |
| Account holder | The holder of the master account, often the platform | Your client |
| Where the money sits | In the master account, split by the provider's records | In your client's own account, with its own balance |
| Name checked by Verification of Payee | Depends on the provider's set-up | Your client's name |
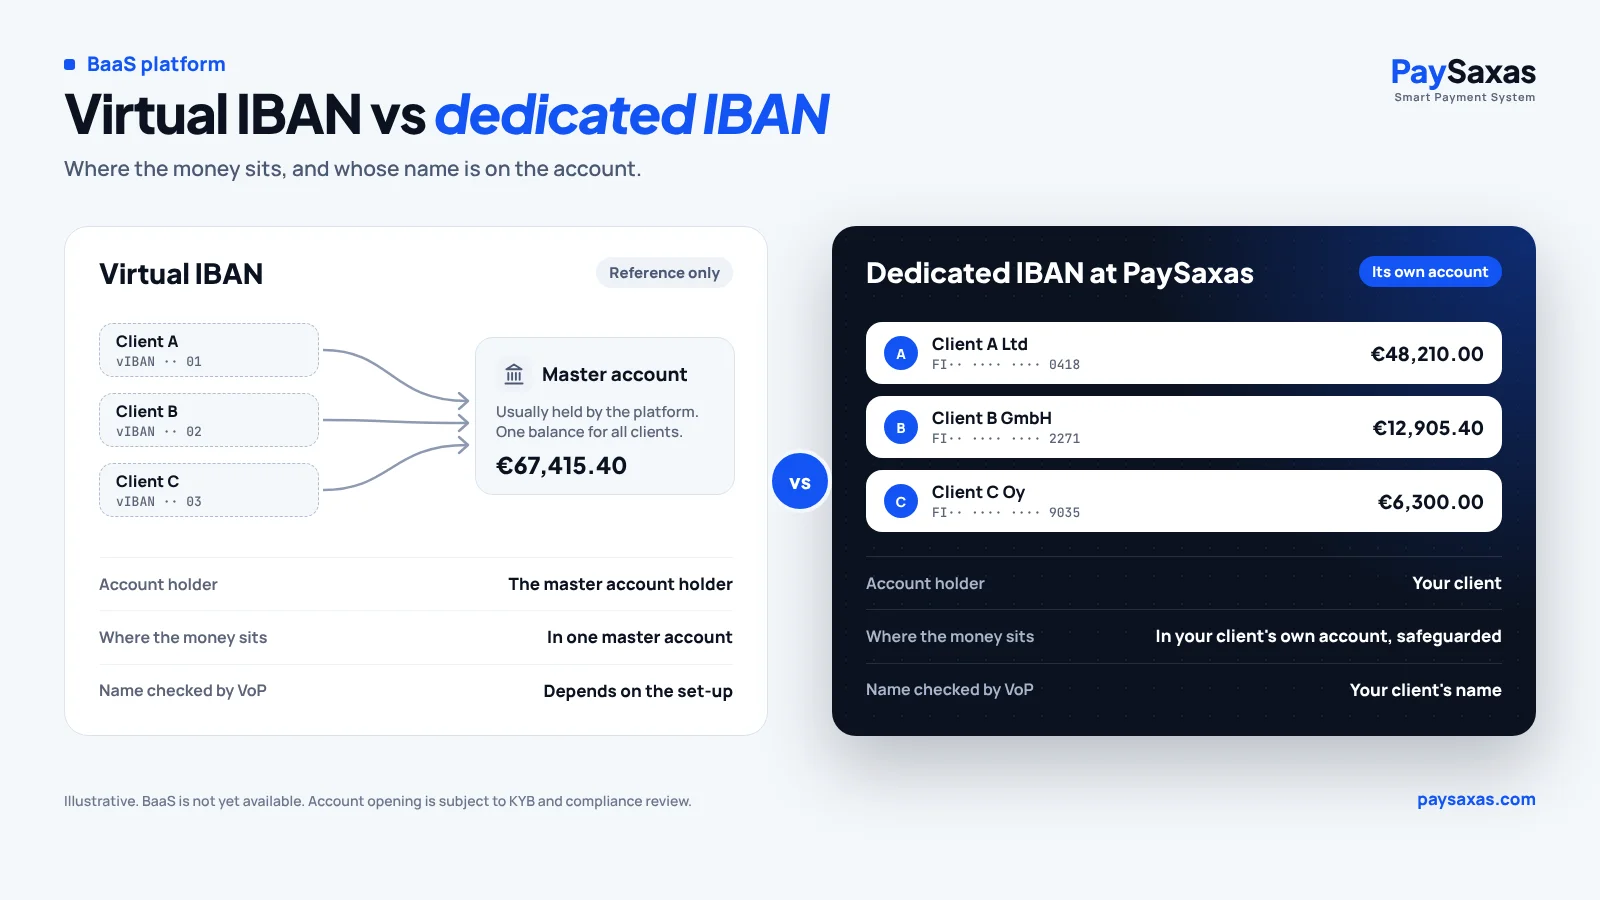
Virtual IBANs have their uses, for example for matching incoming payments. But when your clients need accounts of their own, with their own balance and their own name on payments, a dedicated IBAN is the model that fits.
What makes the PaySaxas BaaS platform different
- Real IBANs, not virtual ones. Every account has its own Finnish IBAN in the holder's own name. We issue each IBAN once and never reuse it, even when an account closes.
- Your clients' names on their payments. Counterparties pay to an IBAN in your client's name, so Verification of Payee checks your client's name, not yours. See why clients see "No match".
- Direct access to the SEPA clearing scheme. Incoming SEPA Instant payments arrive in seconds, any day of the year. Payments between PaySaxas accounts also go through instantly, as internal transfers.
- Verification of Payee on outgoing payments, as an additional layer of protection: the payee's name is matched against the IBAN before the payment leaves. The European Payments Council sets the scheme rules.
- Payments approved with strong customer authentication. An API key alone does not move money: a person authorised on the account approves each payment.
- One dashboard and one API with the same functions. Your team and your product therefore work with the same accounts and the same data.
- Compliance on every account. Every account holder goes through KYC or KYB with PaySaxas, and we also screen and monitor every account.
- Safeguarded funds. Money on PaySaxas accounts is safeguarded in accordance with regulatory requirements and reconciled daily.
- A licensed EMI in Finland. PaySaxas Oy is an electronic money institution supervised by FIN-FSA. You can also check it in the EBA register.
- A dedicated account manager from onboarding, who stays your point of contact, knows your business and helps with day-to-day questions.
Who the BaaS platform is for
The PaySaxas BaaS platform is built mainly for regulated businesses that want to offer EUR accounts to their own clients:
- EMIs and payment institutions in the EU, the EEA and the UK that want EUR accounts with SEPA for their clients without building their own banking set-up. For example, a UK EMI that wants to offer EUR accounts to its clients after losing EEA passporting.
- MSBs and PSPs in Canada that want a named EUR IBAN for each business client, for its European receivables.
- Crypto businesses, such as MSBs, VASPs and CASPs, whose clients want IBANs in their own names. See our guide to crypto exchange banking.
- Regulated firms in other markets, such as the UAE, Latin America and Asia-Pacific, whose clients need EUR accounts.
- Any business client of PaySaxas that wants to connect its own accounts to its systems, for example for payroll, supplier payouts and reconciliation.
To open accounts for your clients or to hold their money, your business needs the licence or registration its activity requires. We assess every partner case by case.
Under one roof with your own accounts
BaaS sits next to the accounts you use for your own business:
- An operational account for your own money: revenue, suppliers, salaries and taxes.
- A pooled account for client money in motion.
- A segregated client-funds account for client balances that stay with you, where your regulator allows it. See how it works in our guide to RPAA safeguarding for MSBs.
- Dedicated IBANs for your clients through BaaS, coming soon.
You can open your own accounts now and add BaaS when it goes live, with the same team and the same account manager. Money also moves between your own accounts by instant internal transfer.
Onboarding: what we look at
Partner onboarding starts with due diligence on your business. During onboarding, expect questions about:
- your licence or registration and the markets you serve;
- ownership and management (KYB) and your AML programme;
- who your clients are, where they are based and how many accounts you expect;
- expected volumes and payment flows;
- how you will use the platform: accounts in your clients' names, client-funds accounts or both;
- whether you will work through the dashboard, the API or both.
When you open accounts in your clients' names, each client also goes through our own KYC or KYB, and the decision on every account stays with PaySaxas. We also review each partnership once a year.
Final thoughts on choosing a BaaS platform
A BaaS platform should give your clients real accounts, not just references. With PaySaxas, every account has a dedicated IBAN in its holder's own name: your clients' accounts, your client-funds accounts and your own. Your team works in one dashboard, and your product connects through one API. In addition, you get one provider and one account manager.
Become one of the first PaySaxas BaaS partners: tell us about your clients, and we will suggest a set-up for your business.
BaaS is not yet available, and the features described may change before launch. Account opening is subject to KYB and compliance review. PaySaxas Oy is authorised by FIN-FSA (Business ID 3387454-8), has its registered office in Helsinki and pays no interest on e-money. PaySaxas is not a bank and does not provide investment advice. E-money is not covered by deposit guarantee; client funds are safeguarded. This article is general information, not legal advice.
FAQ
What is a BaaS platform?
A BaaS platform lets a business offer accounts and payments to its own clients through a licensed provider. The provider holds the accounts and runs the compliance checks. The business then manages the accounts through a dashboard or an API.
What is the difference between a virtual IBAN and a dedicated IBAN?
A virtual IBAN is a reference that routes payments into a master account held by someone else. A dedicated IBAN belongs to an account of its own, in the client's own name and with its own balance. PaySaxas BaaS uses dedicated IBANs only.
Who holds the account: my business or my client?
It depends on how you use the platform. With accounts in your clients' names, your client holds the account. It goes through KYC or KYB with us and accepts our terms, and you then manage the account under its mandate. With client-funds accounts, your business holds the accounts in its own name, apart from your own money.
Can I use the BaaS API for my own accounts?
Yes. Any business client of PaySaxas can connect its own accounts to its systems. For example, it can send payouts from its ERP and bring incoming payments into its ledger.
Can I use the BaaS dashboard without the API?
Yes. The dashboard and the API are built to do the same things, so you can work in the dashboard first and connect the API later.
Which payments does the BaaS platform support?
EUR payments by SEPA transfer, including batch payouts. Incoming SEPA Instant payments arrive in seconds any day of the year, and payments between PaySaxas accounts go through instantly as internal transfers. A person authorised on the account approves each outgoing payment with strong customer authentication, and Verification of Payee runs before it leaves.
Who can become a PaySaxas BaaS partner?
Regulated businesses, such as EMIs, payment institutions, PSPs and MSBs, that hold the licence or registration their activity requires. A partner also holds its own account with PaySaxas, and we assess every partner case by case.
When will PaySaxas BaaS be available?
Soon. You can open your operational and pooled accounts now and add dedicated IBANs for your clients when BaaS goes live. Contact us if you want to be among the first partners.